The yearly charge on your assets
We explain what counts as an asset, how the charge works and which parts stay outside it.

You have lived here a while and your savings are growing. We show you what to weigh for the long run and where each answer lives.
How is this page fact-checked?
We check every page for accuracy, timeliness and relevance. Each one is written and reviewed by our qualified advisors, so the information stays clear, complete and correct.
Updated 6 October 2026
Your long view
Thriving in the Netherlands means your money now has a long horizon here. Three things start to matter more than your yearly tax return.
The first is how the Dutch system treats what you have saved and invested. The second is how much Dutch pension you are actually building. The third is what your income looks like once the 30% ruling ends.
None of that is urgent in a single year but all of it compounds. So we look at the three together. And we point you to the page that answers each question in full.
Where to start
Most people at this stage arrive with one of these five. If none of them fits, Book your free call
Tax, pension, mortgage and insurance all pull on each other. See how we bring the four together.
This is meYour wealthYou hold more than a buffer but have no plan for the rest. See what a position that size asks of you.
This is mePension checkOld jobs, years abroad and a scheme you never read. See how we map what you have built so far.
This is meBuilding moreFreelance years and thin schemes leave room to fill. See how much you can set aside with tax relief.
This is meSavingsA savings plan is the calmer route. You still need to choose the right one, so see how much of it stays tax-free.
This is meAre you earlier in your Dutch life? Is your money abroad? Then See all situations.
Your assets
If you live in the Netherlands, most of what you own falls in Box 3. You pay it each year on what you own, not on the profit you made. So a quiet year still counts.
The rules here are moving. And the 30% ruling has an end date. These three pages give the detail. Some of your wealth sits abroad? Then read about assets abroad.
We explain what counts as an asset, how the charge works and which parts stay outside it.
We follow the move towards a charge on real return, what already stands and what still has to land.
We show what shifts in your net pay and in your assets. And how much notice you get first.
Your pension
Dutch pension comes in layers. The state layer is the AOW. You build it up for every year you are insured here. Years spent abroad often leave a hole in it. Want to know what that gap means? Read about the pension gap.
On top of that sits whatever your employer arranges and whatever you put aside yourself. Making those three layers visible is usually the first honest surprise of a long-term plan. A pension from another country sits alongside these Dutch layers.
We walk you through the layers, the age it starts and what happens to your income.
Two systems, one retirement. We work out which country may tax what. And what your Dutch return has to show.
We explain how an annuity turns a lump sum into a fixed income. And when it is the wrong tool.
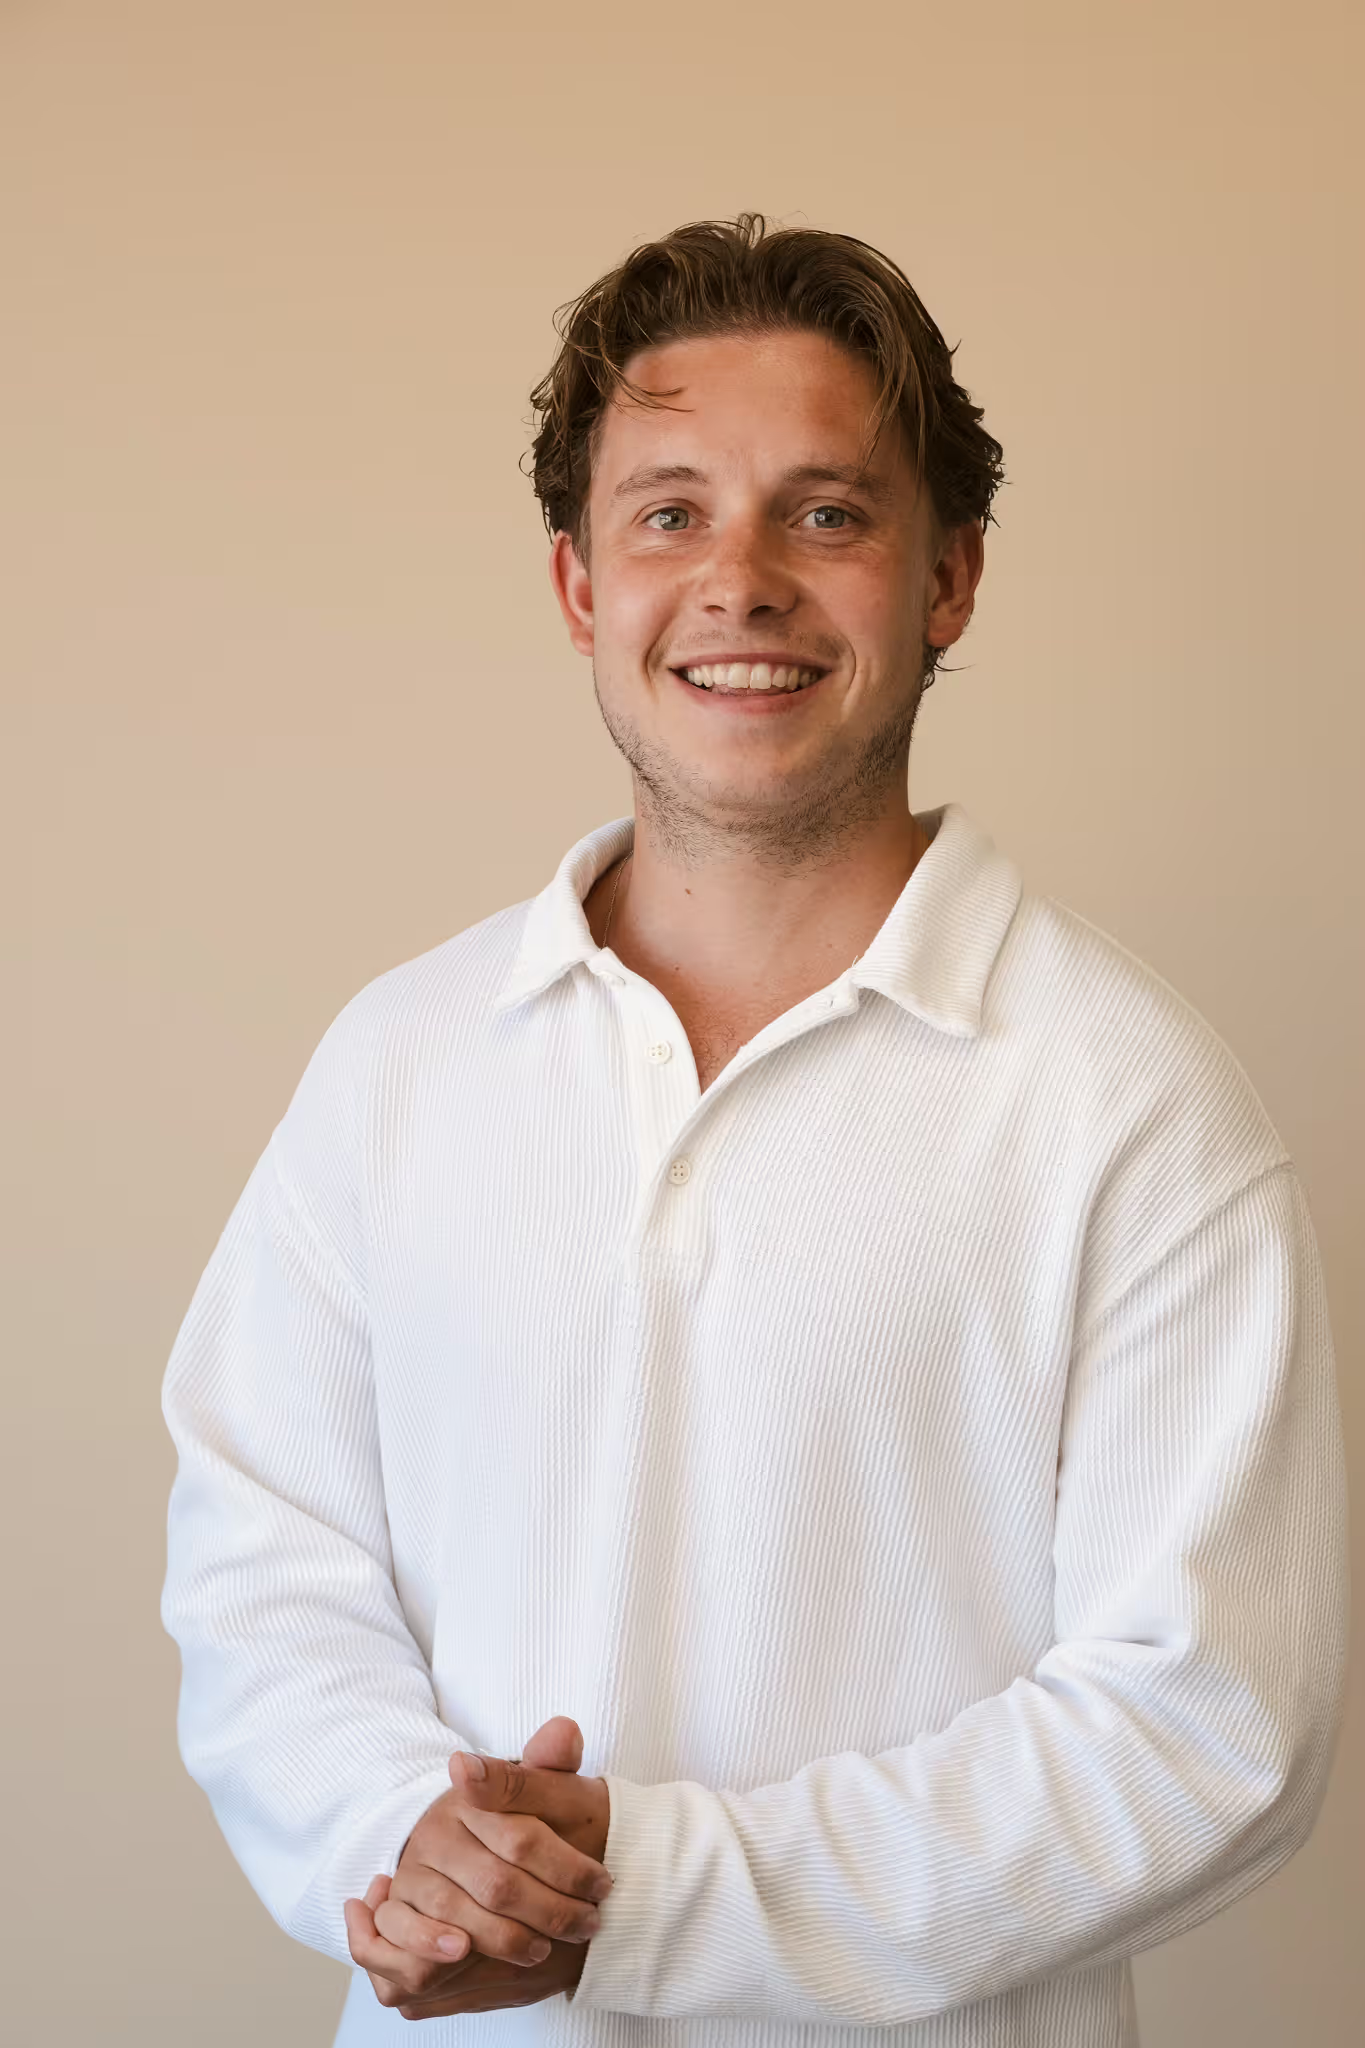
“Most people I speak with are not behind at all. They have simply never seen the whole thing on one page. That is what a first conversation is for.”
Menno van der Made
Tax advisor
Your advisor
You speak with one advisor who already knows the Dutch system. He sees how your return, your savings and your pension fit together.
Pick a slot this week. We map your situation and you decide what happens next.
Send it on WhatsApp and you get a straight answer back.
Call the office and we put you through to an advisor.
Frequently asked
Five questions we answer most once you have been here a few years. Ask Menno
Next step
We start from what you already have rather than from a product. We map what needs attention and what does not. Bring your latest pension overview to that first call.
What's included
A dedicated advisor
Help in English or Dutch
You're not committing to anything.
Essential cookies keep this site working. With your permission we also use statistics cookies, to see how the site is used and improve it, and marketing cookies, so we can show you our ads. You can change your choice at any time via 'Cookie settings' at the bottom of every page.