TaxSavers Financial Services
Mortgage Advice Dutch House
Mortgage advice

Your Dutch mortgage, clearly arranged.

Mortgage advice for internationals in the Netherlands, including the 30% ruling, temporary contracts and non-Dutch documents.

We look at your situation and explain your options. Our associated company, a separate licensed advice firm, advises on and arranges the mortgage itself.

Written by
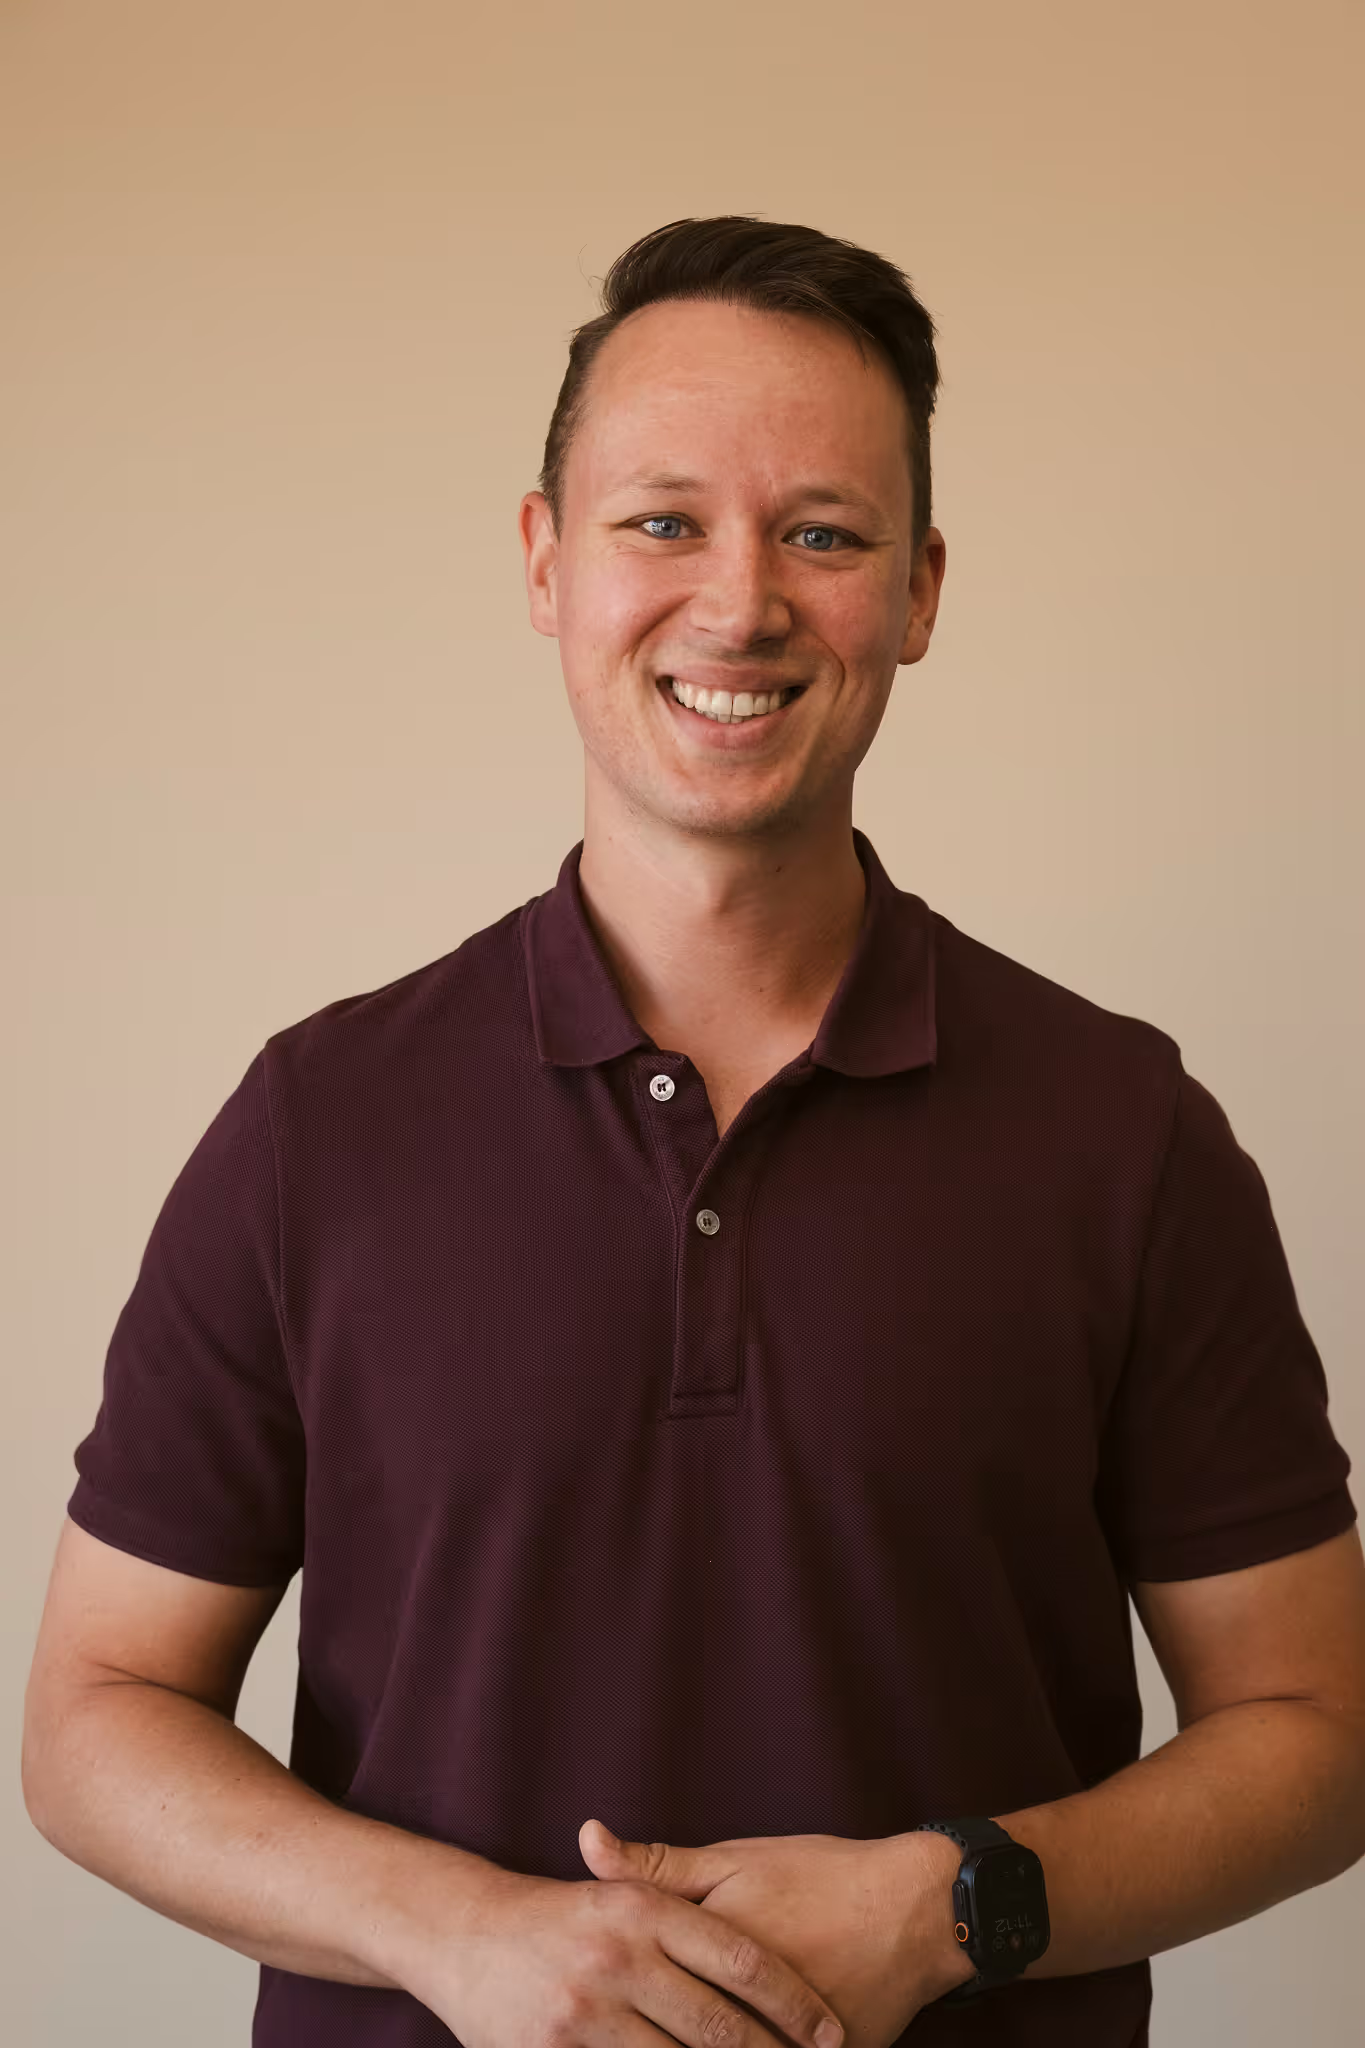
Tim van HulstTeam Lead Mortgage
Reviewed by
Kim van der MandenCertified Mortgage Insurance and Wealth Advisor
Updated 20 October 2026
5.0/5on Google, 1,500+ reviews
€650M+ arrangedin Dutch mortgages
from €2,750advice fee for your situation, agreed up front
30+ lenderscompared side by side
Mortgage quick scan

See what you can borrow in 2 minutes.

Answer a few questions about your income, 30% ruling and contract type. We'll show you a realistic borrowing estimate, built for internationals in the Netherlands.

Mortgage quick scan
  • Free, no account required
  • Includes 30% ruling and temporary contract situations
  • Indicative borrowing estimate

Indicative only, final advice follows after a personal advisor review.

You could borrow

Indicative

0

Approx. €1,934 / month · 30-yr fixed at 3.8%

Financial overview

Buyer costs

€8,470

Transfer tax and notary fees, based on your answers

Renovation

€25,000

Estimated budget

Time to result

~ 2 min

After submission

What we cover

Mortgage questions where your situation is not entirely standard.

Mortgage arranged through our associated company. We take on the tax that follows.

What our associated company does for you

They give the mortgage advice and arrange the mortgage. They prepare your application and guide you to completion.

What we do

We help internationals with mortgage questions in the Netherlands. We map your situation, explain your options and hand over.

We list what may affect your mortgage choice: the 30% ruling, temporary or freelance income, residency status, non-Dutch documents, foreign income, second homes, pensions and changing plans. Read how the 30% ruling affects what you can borrow.

Director-shareholder (DGA) of your own BV, a Dutch private limited company? Mortgage for business covers how lenders assess your income and what a BV means for your mortgage. Same advisors, same standards, different page. Moving abroad later? They can explain what that means for your mortgage. We cover what it means for your tax.

Want to read up first? See our pages on the first-time buyer mortgage, refinancing, the self-employed mortgage and the family mortgage. Buying on ground lease? Our erfpacht guide explains it. The mortgage calculator gives you a first estimate of what you can borrow.
Mortgage Advice Netherlands
How it works

Four steps, from insight to decision.

Step 2

Advice and arrangement

From here our associated company takes over: they advise on the mortgage, arrange it and take it out with you. Their advisor compares the Dutch lenders that fit your situation.

You leave with You get a written recommendation, and you do not start over.
Step 3

Application & explanation

You get your application prepared, the right documents collected and your situation explained to the lender.

You leave with You get a complete application with solid supporting information.
Step 4

Offer & completion

After approval, you get the final documents checked and guidance all the way to completion.

You leave with You know what needs to happen before you sign. Most files run 8 to 12 weeks from intro call to signing.

Ready to see what you can borrow?

Free scan, no obligation.Fixed fee, agreed up front.

Packages

What fits your mortgage question?

Not every situation needs full mortgage advice straight away. Sometimes a quick scan or short intro call is enough to see where you stand. If more is needed, we'll tell you honestly what the next step should be.

Already a TaxSavers tax client? You get €250 off full advice.

Running a business or buying through a BV, a Dutch private limited company? Mortgage for business →

How pricing works · Who is responsible · Complaints

Mortgage advice is provided by our associated company A&H Finance. They advise you, arrange the mortgage and invoice you. Your agreement for this advice is with them and they are responsible for the service. TaxSavers introduces you and is not a party to that agreement. Do you have a complaint about the advice? Raise it with them first. If you do not reach a solution together, you can take it to Kifid. Kifid is the Dutch complaints institute for financial services. They are registered there and have accepted binding advice, so a Kifid ruling binds them.

They disclose the fixed fee in writing before their advice starts. They do not accept lender commissions. Dutch law forbids them for mortgage intermediaries, a rule called the provisieverbod. Extra complexity is quoted separately before any work starts, never billed by surprise.

Tim van Hulst
Online now

“The bank will tell you what you qualify for. My job is to map your full situation first. Your income, your ruling, your plans five years from now. I explain what that means in plain English, before you sign anything.”

Tim van Hulst

SEH-certified, a Dutch mortgage advisor qualification15+ yrs with internationalsEN · NL

Your advisor

Quick answers to your mortgage questions.

Talk to the advisor who knows your file and picks up when you call. Tim works for A&H Finance, our associated company.

Full mortgage support, start to finish
Beyond your bank

More lenders than your bank.

At your bank, you get mortgage advice based on that bank's own products. Through our associated company, you get a comparison across multiple Dutch lenders and a full look at your situation. We explain what each option means for your tax. That way your mortgage fits not only today, but also what may change later.

At your bank
The wider optionOur way
Lenders
At your bankOne lender
The wider optionMultiple Dutch lenders
Advice
At your bankOwn mortgage products
The wider optionPersonal advice, not a product list
View
At your bankOnly your mortgage
The wider optionYour full situation, including international ties
Fit
At your bankAdvice based on that bank's options
The wider optionAdvice that fits your wider situation
Book your free callAfter the call, you'll know where you stand.

Situations we often see

Real questions. Clear answers.

30% ruling + temporary contract

"Can we buy with a 2-year contract and the 30% ruling?"

A couple in Amsterdam, one on a 2-year tech contract with the ruling, one freelancer. Lenders treat these profiles very differently. A comparison of seven lenders turned up two that accepted both incomes at full value. The mortgage then took shape around the ruling expiry. Their borrowing capacity turned out significantly higher than what their own bank had quoted.

  • 30% ruling
  • Temporary contract
  • Dual income
Non-EU buyer

"Can I buy before my permanent residency comes through?"

A non-EU buyer with a pending IND decision. Most lenders require permanent residency, but three accept alternatives: a higher down payment, shorter fixed terms, or additional documentation. Mapping the options secured approval faster than the buyer expected. IND is the Dutch service that decides on residency permits.

  • Non-EU
  • Pending residency
  • Alternative structures
Refinancing

"Is it worth breaking my fixed rate now?"

A homeowner with a fixed rate from 2023, looking at lower current rates. Modelling weighed the break fee against the long-term savings across multiple lenders. The net benefit turned out to clearly outweigh the costs, something that wasn't obvious before running the numbers.

  • Refinancing
  • Break fee
  • Lender switch
Expiring 30% ruling

"My 30% ruling ends in 18 months, what about my mortgage?"

A tech worker planning to stay in NL past the ruling. Modelling covered the income drop post-ruling and shaped the mortgage so the monthly payment stays manageable after. A longer fixed period locked in a known cost across the transition and removed the uncertainty.

  • 30% ruling expiry
  • Affordability
  • Fixed-rate strategy

Reviews

What internationals say

Read all 1,500+ reviews on Google

I was an absolute pleasure working with Tax Savers. Professional, efficient and very knowledgable

G
George Nel
TaxSavers experience · May 2026

Gertrud provided clear and helpful guidance with my mortgage-related tax return and was very quick and responsive to my questions and emails. Highly recommended.

M
Marc Safa
Income tax return · August 2025

Very responsive and professional services for English speaker clients. They explained everything and they found the best solution for our cases. We are very satisfied with their services.

G
Gelena Vougianovits
TaxSavers experience · April 2026

Frequently asked

A question about your Dutch mortgage?

Here you'll find clear answers to common mortgage questions. If your question is not listed, ask an advisor directly. Ask your advisor

Can internationals actually get a mortgage in the Netherlands?
Yes. Internationals can often get a mortgage in the Netherlands. The right route depends on your income, contract type, residency status and documentation. Some Dutch lenders are more flexible with international situations than others. You see in writing which lenders were compared and why. We help you understand which options are realistic before you apply. No Dutch credit history yet? Lenders then look closely at your income documents.
How does the 30% ruling affect my borrowing capacity?
It depends on the lender. Some lenders take more of your income into account than others when the 30% ruling applies. That can make a meaningful difference to your borrowing capacity. You get a comparison of lenders against your situation. Read our guide to the 30% ruling for the income rules.
What about temporary or contract work?
A temporary contract is not always a deal-breaker. Some lenders accept temporary contracts, especially with the right employer statement or income history. The strategy depends on your contract type, your employer, your income and how long you have been in the Netherlands.
Can I get a mortgage without a BSN or permanent residency?

Not usually without a BSN. With pending or temporary residency status, there may still be options, depending on your situation. Some lenders require a residence permit that covers the fixed-interest period. Others may accept alternative structures. We map the options before you commit to a full advice process.

A BSN is your Dutch citizen service number.

Do you compare multiple Dutch lenders?
Yes, through our associated company. You get a comparison of suitable Dutch lenders that looks beyond the interest rate to conditions, flexibility and documentation requirements. It also considers how each lender reads your international situation.
What does mortgage advice cost? Are there hidden commissions?
Full mortgage advice costs from €2,750, the exact fee agreed with you up front, so there are no surprises. No commission from lenders. Dutch mortgage intermediaries are not allowed to take lender commissions (the provisieverbod). You pay for the advice, which keeps the mortgage recommendation focused on what fits your situation.
How long does the full process take?
Usually 8 to 12 weeks from intro call to signing, depending on your situation and the lender. The quick scan takes around 2 minutes. After that, the intro call and advice process help determine which route is realistic and what documents are needed.
Are you authorised to give mortgage and insurance advice?
TaxSavers advises on tax, not on mortgages, insurance or pensions. For those we work with A&H Finance, a trade name of New Business Group B.V. They hold the AFM licence (12017511) and they advise and arrange. The AFM is the Dutch authority that supervises financial firms. We introduce you and take on the tax that follows.

Your Dutch mortgage

Ready for your next step?

Start with the quick scan or book your free intro call. The scan takes two minutes. The call takes thirty.

What's included

  • Advice across Dutch lenders

  • One fee for the whole advice process

  • Help in English or Dutch