Mortgage advice
For anyone who wants the shape of it first: which lenders suit you and what they check. It is the broadest of the three.

Arranging a mortgage here, changing the one you have or putting it in your return. A permit or foreign income shapes the first. Start with the question that is yours.
Where to start
Yes. Our associated company, a separate licensed advice firm, arranges the mortgage. We take on the tax that follows.
Tim works for them, our associated company, and is your point of contact throughout the advice. Rates and borrowing figures come up in mortgage advice.
This page covers the home you live in. A rental or a holiday place follows other rules.
We advise on tax. Insurance and pension advice work the same way.
Arranging a mortgage
Which of these three describes you?
Full picture first. You want an overview before you pick a route.
A first purchase. You are buying for the first time here.
Your own business. You run a business of your own.
A permit or income from abroad changes which lenders will look at you. Which lender fits is a conversation rather than a calculation. It is what mortgage advice is for.
The three pages below take those starting points one at a time.
Buying a home on leased land? The erfpacht page sits further down.
Borrowing from family for the purchase? The family mortgage page sits further down too.
For anyone who wants the shape of it first: which lenders suit you and what they check. It is the broadest of the three.
For a first purchase in the Netherlands, including what a temporary contract or a recent arrival means for it. It assumes you have not done this before.
For freelancers and business owners, whose figures a lender reads differently from a payslip. It covers what they ask for and how far back they look.
Your current mortgage
Then the question is usually whether it still fits. Rates move and incomes change. The mortgage you took out then was built for a different life.
Each page below covers something that changes the cost or the tax treatment. Pick the one that fits your own mortgage. Leaving the Netherlands and keeping the home? Let us know.
For a mortgage you already have and want to move or renegotiate. It covers when switching is worth looking at and what doing it costs.
For borrowing from a parent or another family member instead of a bank or alongside one. It sets out how the Belastingdienst (Dutch tax office) treats that loan.
For a home on land you lease rather than own, the erfpacht arrangement. It explains what the ground rent is and how the Belastingdienst treats it. It suits buyers and owners alike.
Tax return
Enough that it is worth going through once and then checking each year. Several parts of it can show up in the return.
The four pages below are part of our tax section. Each one is about the return rather than the mortgage. Read the one that matches your own return.
Leasehold and a family loan also affect your return.
Do you own a home abroad as well? Say so when you call.
For the interest you pay on the loan for the home you live in, which is deductible under conditions. The page sets out which conditions.
For the boeterente, the early-repayment penalty a lender charges when you repay or switch ahead of time. It explains when that charge is deductible.
For the bouwdepot, the sum a lender holds back for building or renovation work. It covers how the Belastingdienst treats the interest on that money.
For the bijleenregeling, the rule that limits your new deductible loan after a sale. It explains how far that reaches.
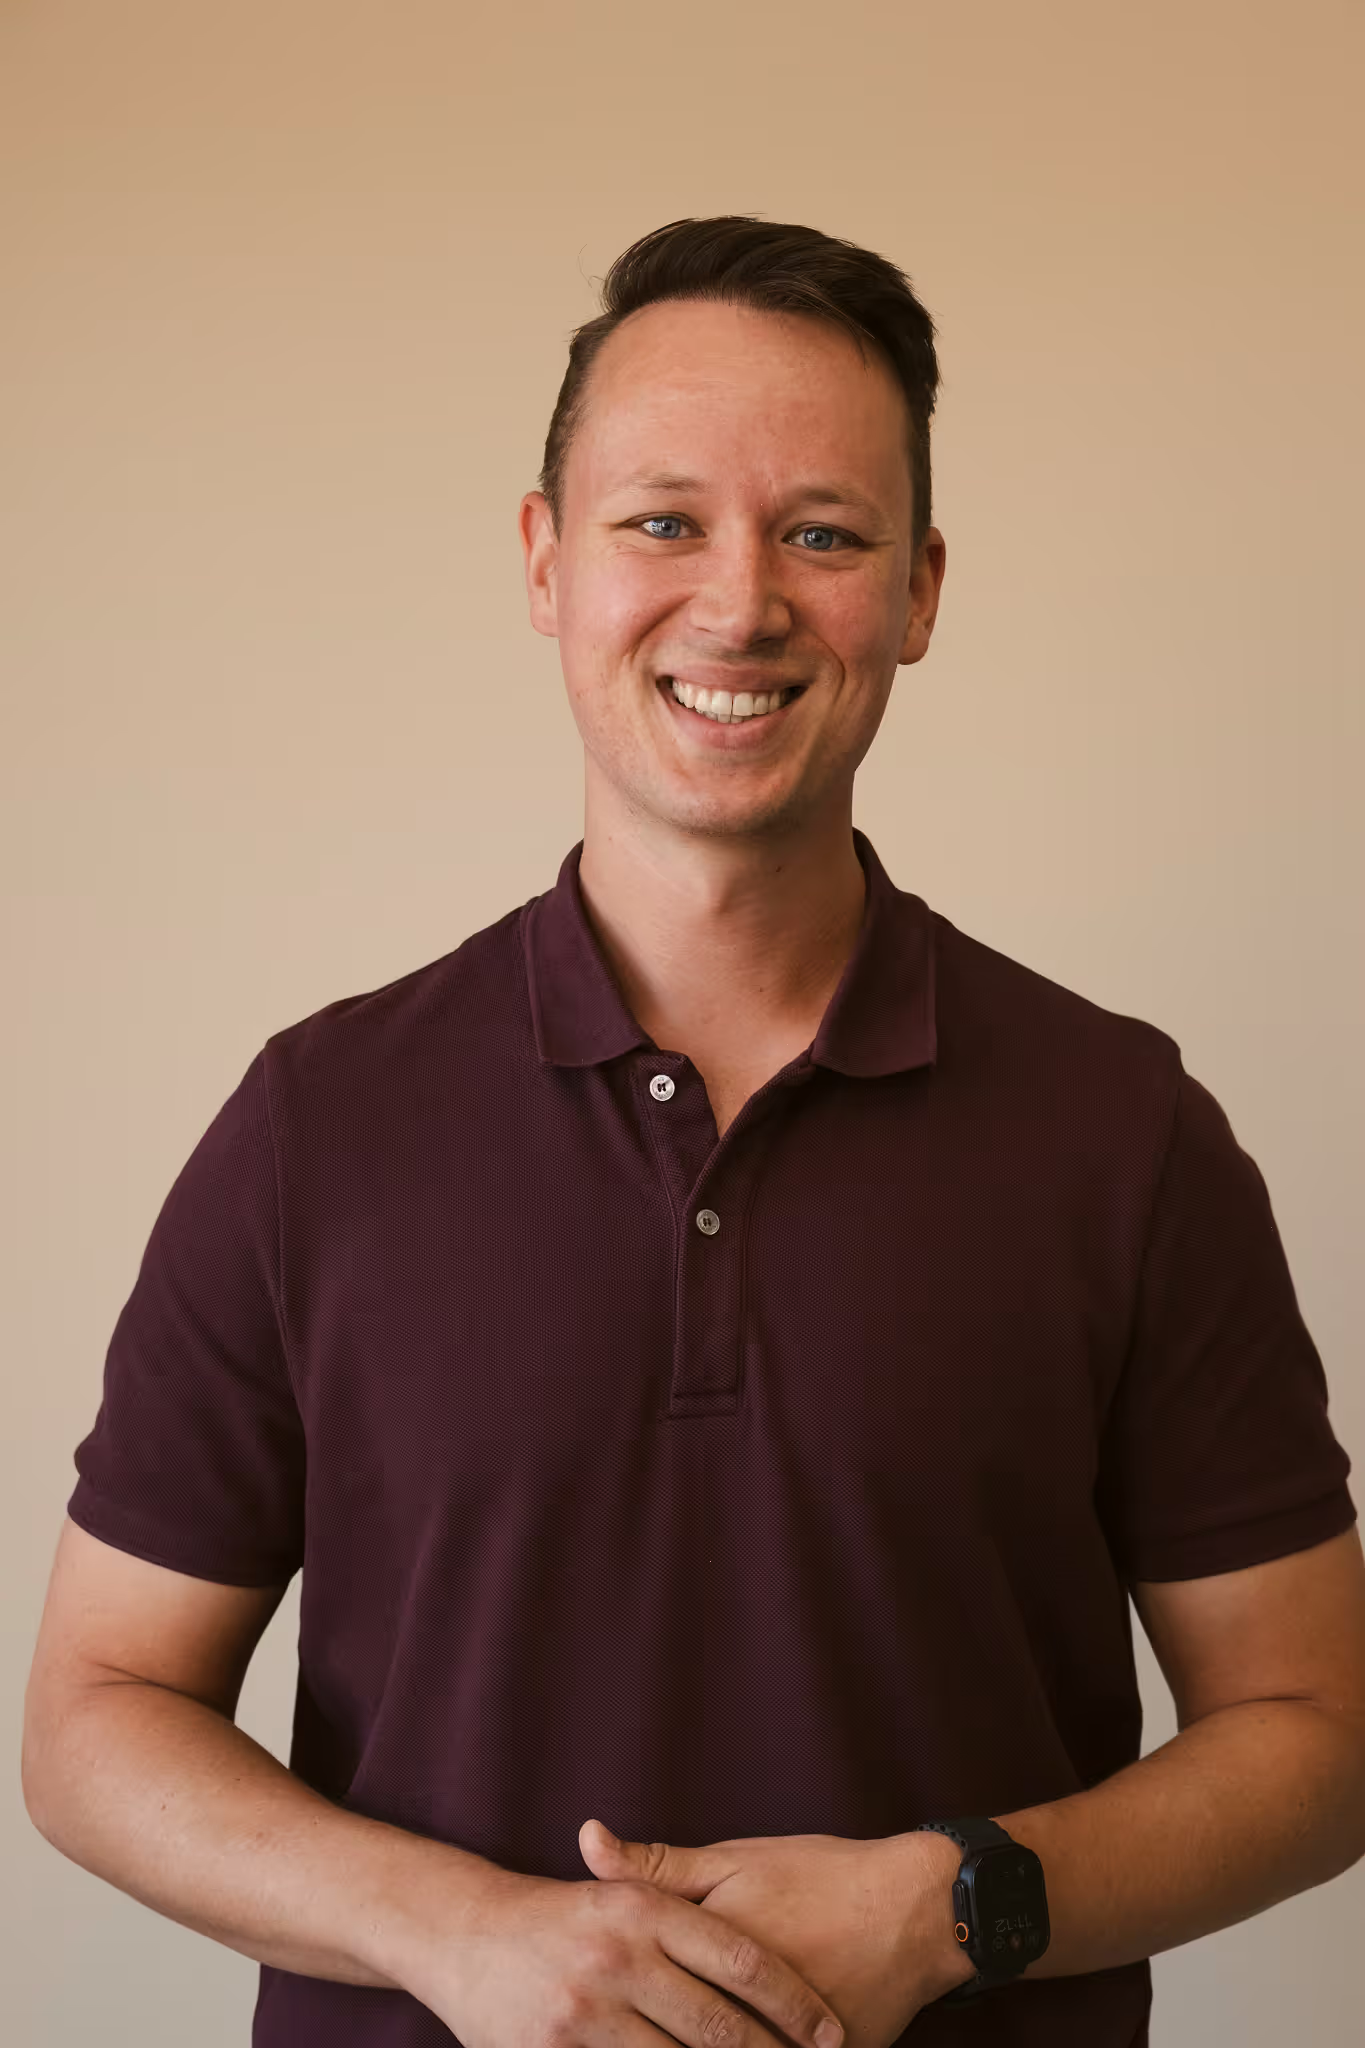
“Most people arrive with one question and find there are three underneath it. I would rather take those apart together than guess at the answer.”
Tim van Hulst
Your contact
You do not have to know the answer before you call. Describe your plan to Tim and he says which page covers it. Tim works for A&H Finance, our associated company.
Mortgage advice is provided by our associated company. They advise you, arrange the mortgage and invoice you. Your agreement for this advice is with them and they are responsible for the service. TaxSavers introduces you and is not a party to that agreement. Do you have a complaint about the advice? Raise it with them first. If you do not reach a solution together, you can take it to Kifid. They are registered there and have accepted binding advice, so a Kifid ruling binds them.
Pick a time that suits you. Bring the plan you have.
Call +31 20 2170120 and ask for Tim.
Send your question when it suits you and pick the answer up later. Handy when you are between things.
Frequently asked
The questions people bring us before they know which page they need. Yours not here? Ask Tim
Your next step
Book a mortgage call and say what you are trying to do. The call itself commits you to nothing.
What's included
We look at your whole situation
One conversation to work out where your question belongs
Your mortgage and your return raised in the same call
Nothing to sign
Essential cookies keep this site working. With your permission we also use statistics cookies, to see how the site is used and improve it, and marketing cookies, so we can show you our ads. You can change your choice at any time via 'Cookie settings' at the bottom of every page.