Health insurance
Each year you can look again at whether your cover still fits. That holds too if part of your life is across the border. You can switch health insurer at the end of each year.
Essential cookies keep this site working. With your permission we also use statistics cookies, to see how the site is used and improve it, and marketing cookies, so we can show you our ads. You can change your choice at any time via 'Cookie settings' at the bottom of every page.

Our associated company, a separate licensed advice firm, arranges the insurance. We take on the tax that follows. They go through your cover and say what you need and what you can drop. Just arrived? Health insurance is the one to sort first.
Dutch insurance
Two insurances are required by law in the Netherlands. One is basic health insurance. The other is car liability cover if you own a car. Once you live here, the Dutch system applies to you like anyone else. Health insurance also works differently from what you probably know.
You have four months from the day you become insurable to arrange health cover. Insurable usually means the day you start working here or register in your municipality. Cover and premiums both run from that day, so arranging it late saves you nothing. Our health insurance page goes into this in more detail.
Part of your healthcare costs each year is yours to pay. That fixed amount is called the eigen risico. In 2026 the eigen risico is €385. Visits to your GP do not count towards it. Children under 18 pay no eigen risico and are covered free with their parents.
The others are a choice. Home, life and disability cover protect what you build here. Liability cover is a fifth that most households take. Car liability cover is the one required insurance this page does not cover. Whether you need the rest depends on your job, your family and your home.
Since 2013 an advisor earns nothing on the sale of life insurance and similar products. That rule is called the provisieverbod. You pay for the advice separately, apart from the product. That advice fee applies to products with a big impact.
Two situations need a closer look: working across borders and running your own business. Raise work across borders in that call, because it can decide which country insures you. Usually the country where you work insures you, even if you live elsewhere. You go through the rest in your first call.
Personal cover
Four covers protect daily life in the Netherlands. They protect your health, your home and your income. Health insurance in particular works differently here than in most countries. The other three will look familiar. Which ones you need depends on your work, your family and your home. You go through them in your first call.
For your business
As a business or freelancer you can insure a lot. Liability and legal aid are the common ones. Some clients ask for proof of liability cover before you start. Working across borders or for foreign clients raises its own questions. You find out which of these fit your work.
Who does what
The insurance advice
Insurance advice is provided by our associated company A&H Finance. They advise you, arrange the insurance and invoice you. Your agreement for this advice is with them and they are responsible for the service. TaxSavers introduces you and is not a party to that agreement. Do you have a complaint about the advice? Raise it with them first. If you do not reach a solution together, you can take it to Kifid, the Dutch complaints body for financial services. They are registered there and have accepted binding advice, so a Kifid ruling binds them.
What we do
We explain how insurance works here and what the rules ask of you. We do that in plain language, in English or Dutch. The tax side stays with us, from premium to payout.
Each year you can look again at whether your cover still fits. That holds too if part of your life is across the border. You can switch health insurer at the end of each year.
This cover protects your home and everything in it. When you buy, mortgage lenders expect it in practice.
If you are no longer there, your family carries on without money worries. This cover often comes with your mortgage. How you set it up decides whether inheritance tax applies to the payout.
Frequently asked
The questions internationals ask us most about insurance here. Yours not in the list?
Insurance advice
You hear which covers fit and which you can drop. Then you decide. Have your current policies ready for the call. There is nothing to sign.
What's included
A dedicated advisor
Advice first, a product only if it fits
If you cannot work for a while as a freelancer, you still need an income. You get cover that matches your monthly costs. The premium is deductible. You pay tax on the payout.
Help in English or Dutch
How is this page fact-checked?
We check every page for accuracy, timeliness and relevance. Each one is written and reviewed by our qualified advisors, so the information stays clear, complete and correct.
Updated 5 August 2026
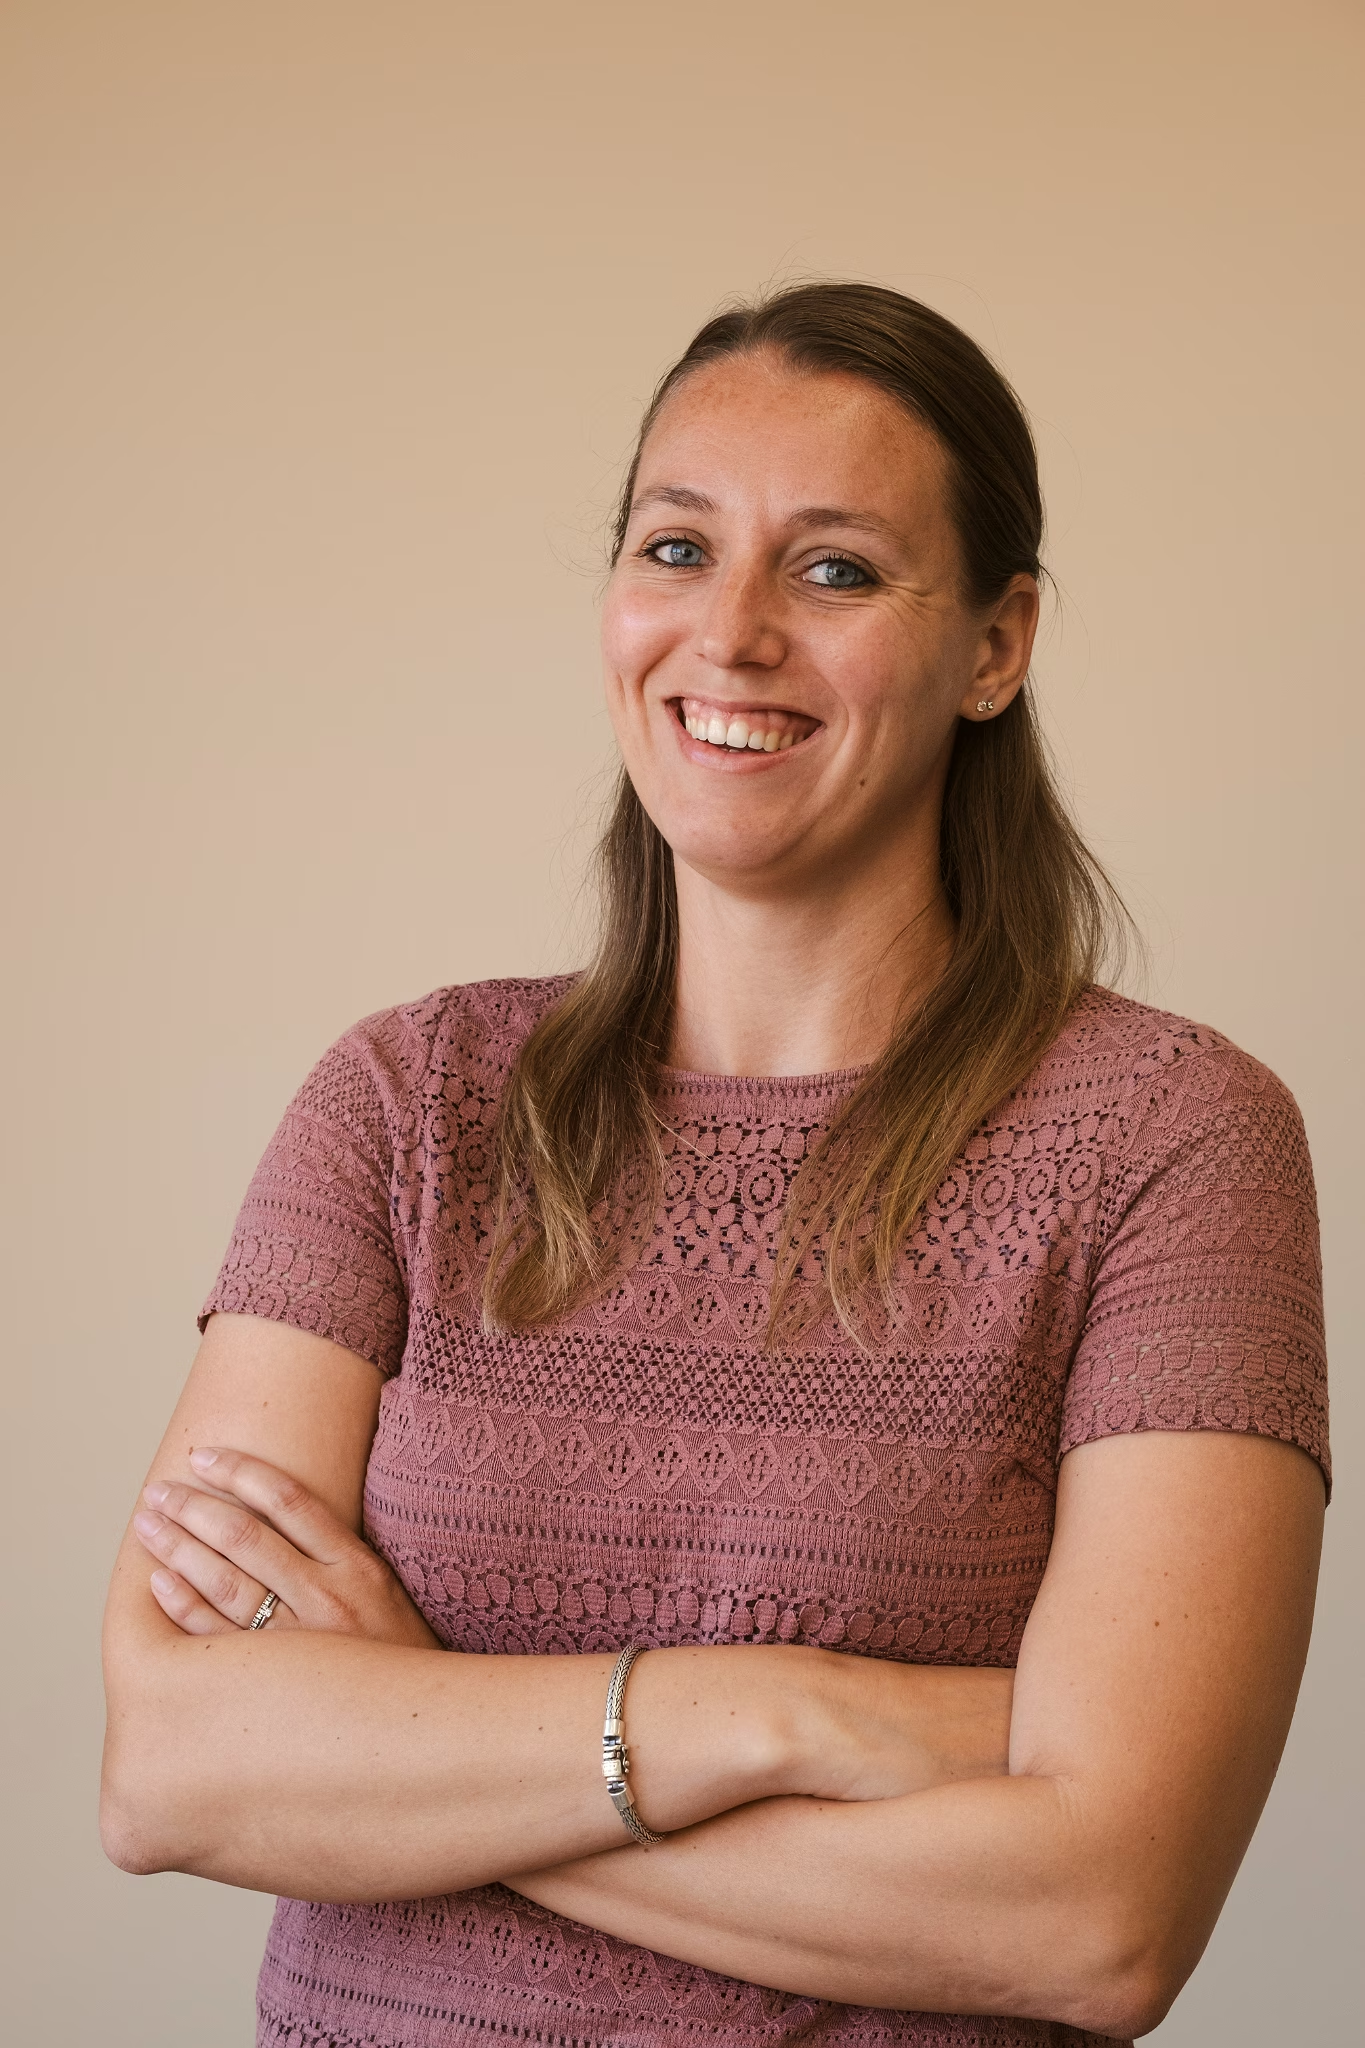
“"Nobody wakes up wanting a policy. You want to know your family and income are safe. I listen to your situation and point you to the right advisor."”
Kim van der Manden
Your advisor
Tell us your situation once. Your advisor picks it up from there. If something ties in with your mortgage or your tax return, you hear that too. If a policy fits, you fill in your details on the next step. We pass them on only once you agree. You keep the same contact. Kim works for our associated company. The insurance advice itself comes from them.
20 minutes, no obligation
An English-speaking advisor replies personally.
+31 20 2170120, for a question that cannot wait.