TaxSavers Financial Services
Two business co-owners in conversation on a wet Amsterdam side street at dusk, the reassurance that key person insurance Netherlands is meant to buy
Key person insurance

Your buy-out clause, checked against the cover

Your agreement already says the survivor buys the shares. Key person insurance in the Netherlands is how that promise gets funded.

We read your agreement and the amount behind it. Our associated company, a separate licensed insurance advice firm, arranges the insurance. We take on the tax that follows. We also check the case where a co-owner or heir lives abroad.

One conversation

we line up your insurance advice and your tax advice

Nationwide

by video call, phone and secure upload

EN · NL

we help you in both languages

Written by
Kim van der MandenCertified Mortgage Insurance and Wealth Advisor
Reviewed by
Tim van HulstTeam Lead Mortgage
Updated 20 October 2026
Three documentsagreement, policy and tax in one review
Two specialistsinsurance advice on one side, tax advice on the other
1 working daywe reply, every time
Free first callpick a time that suits you

Agreement and policy

Key person insurance Netherlands starts with three documents

Three documents decide whether your buy-out clause works: the agreement, the policy and the tax. You may have the agreement. Whether the policy and the tax match it is the open question.

Your shareholders’ or partnership agreement already names who buys the shares when a co-owner dies. In Dutch that clause is the overnamebeding. It rarely says where the money comes from.

Your agreement also sets the share price. Is it a fixed amount, a formula or a valuer’s call at the time?

The cover itself is one simple product. It pays a fixed amount if the insured person dies. Personal life cover for a mortgage or your family has its own page. Add any business debt held in your name to that share price.

Two business co-owners walk the gravel path through a botanical palm house at first light

Policy set-up

Who owes the premium decides the tax

The test is who owes the premium, not who pays it. You agree that liability with the insurer. It then has to show in two places: the signed and dated application form, plus the policy or clause sheet.

With two co-owners the cover is written crossways. The Dutch term is kruislings verzekeren. You are the policyholder on your co-owner’s life and you owe the premium there. Your co-owner does the same on yours.

With three or more owners it is no longer a simple cross. You get a structure designed to fit, not a copied template.

There is one more condition. The tax authority can read two crossing policies as one construction. Their terms and premiums track each other, so it does not weigh them one by one.

Who owes the premium decides the tax, so we check that. We read the application form and the policy next to your agreement. Then we say plainly where the tax risk sits.

Does a co-owner or an heir live outside the Netherlands? Then residence and any treaty decide who taxes the payout. We go through that with you.

Our page on Dutch inheritance tax explains what the payout can cost.
A business owner stands at the rail of a fourth-floor gallery walkway above the autumn mist
How it works

Four steps, no guesswork

The routes

We map the two constructions

Privately between owners or inside the company. We sketch what each route changes for you.

You leave with the two routes side by side, in outline.
Your decision

You choose the route that fits

You get the scope in writing before any work starts. Nothing moves until you say so.

You leave with the scope on one page, before you decide.
Set up

Advice and arrangement

Kim, at our associated company, lines up the application, the policy and your agreement. Then Kim arranges the cover with you.

You leave with cover written to the person your agreement names.

Ready to check your agreement?

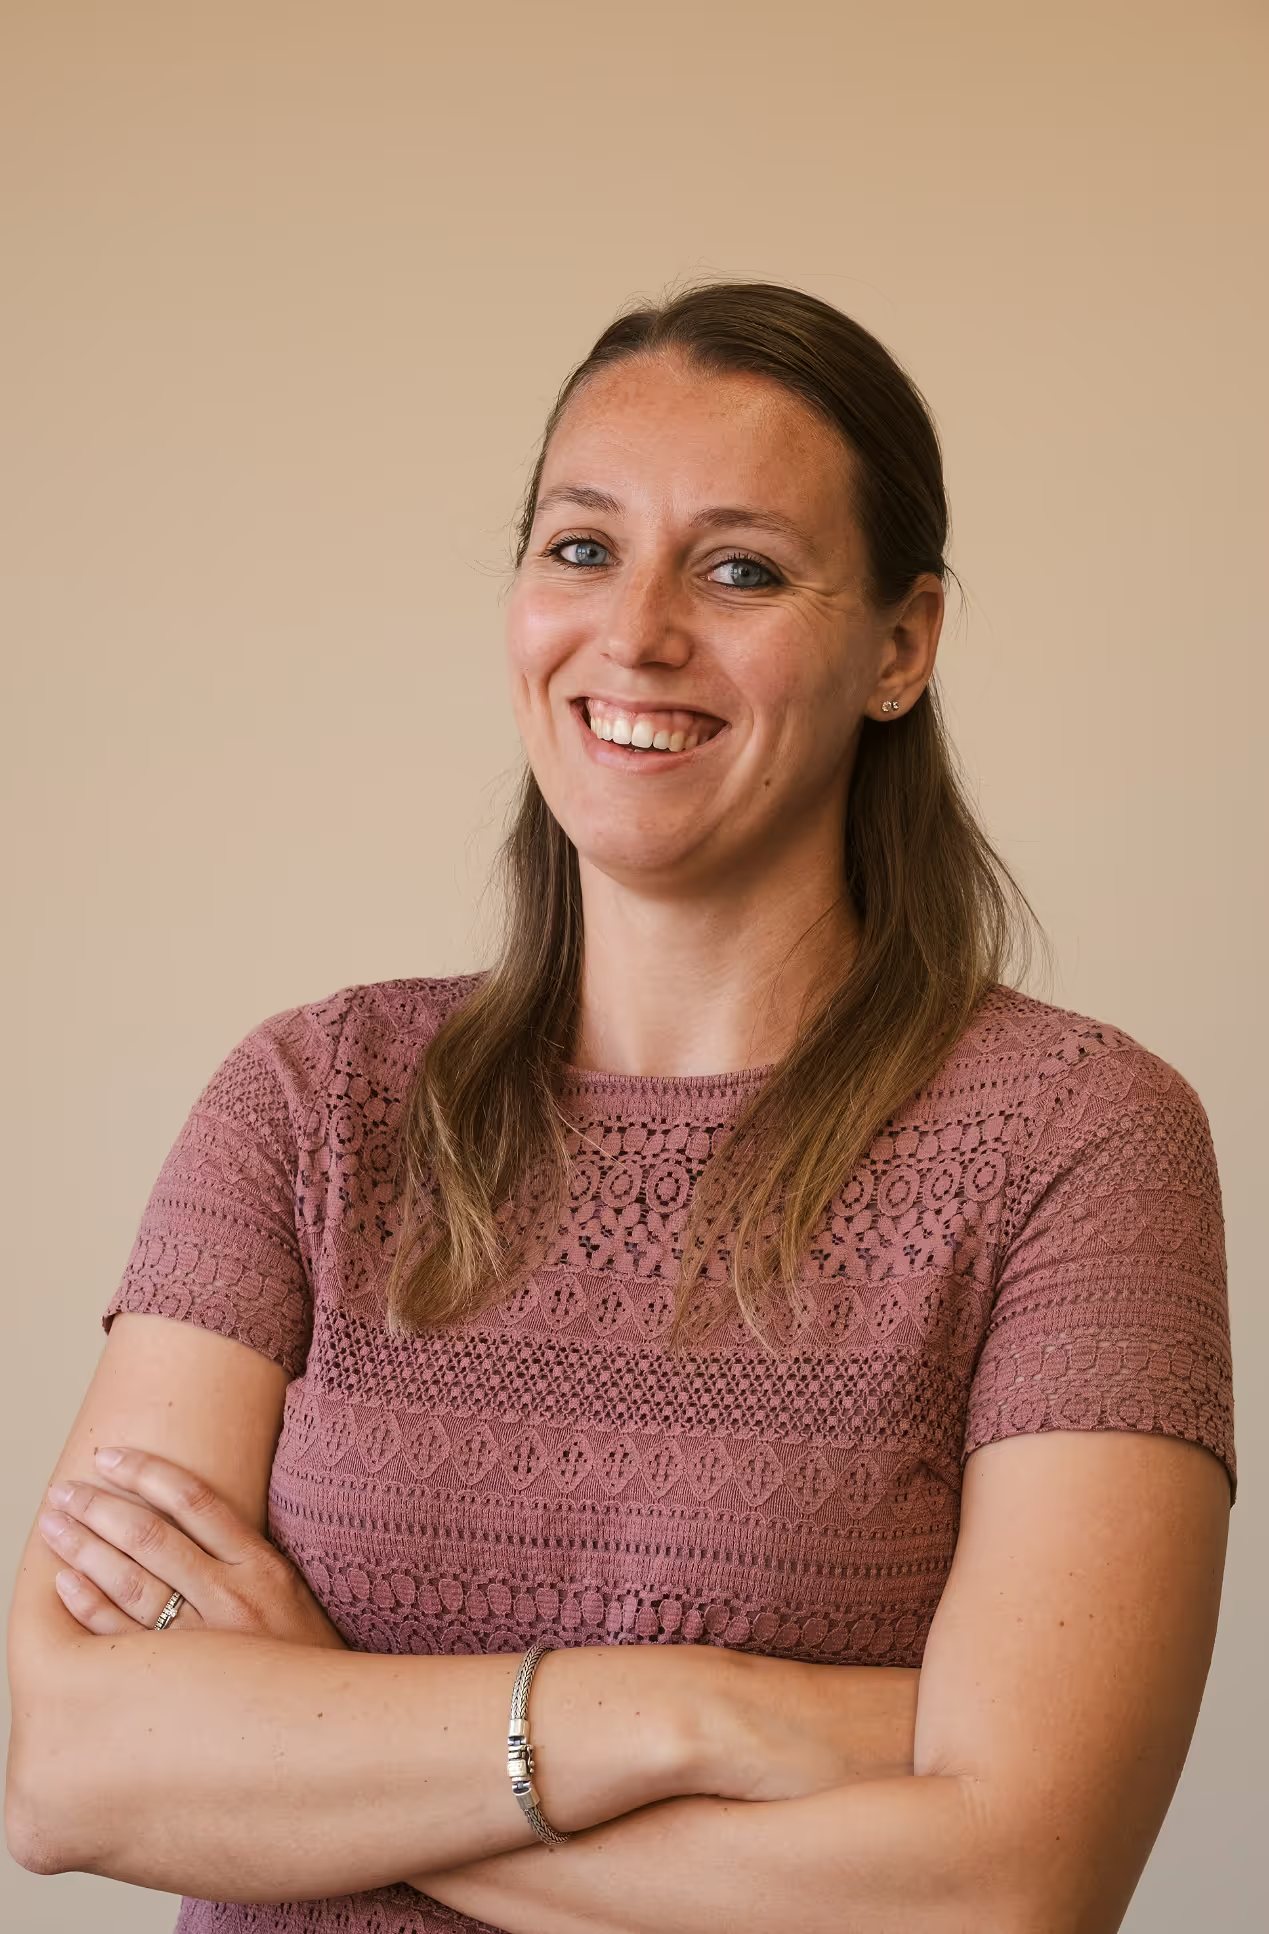
Kim van der Manden
Replies within one working day

“Most agreements I read are fine. What is usually missing is the money behind them. Often nobody has looked at it since the day you signed it. So that is where we start.”

Kim van der Manden

EN · NL

Your advisor

Talk it through with Kim

You speak with Kim directly. Kim works for A&H Finance, our associated company. Kim stays your point of contact throughout.

Insurance advice and tax advice, coordinated together in English and Dutch.

What each option covers, starting with a first conversation

Your advisor starts with a first conversation about what fits your situation.

You decide what happens after the first conversation.

The premium itself is set by the insurer. You get advice on the construction and a check on the paperwork behind it.

Who advises you

Insurance advice is provided by our associated company A&H Finance. They advise you and arrange the insurance. Your agreement for this advice is with them and they are responsible for the service. TaxSavers introduces you and is not a party to that agreement. Do you have a complaint about the advice? Raise it with them first. If you do not reach a solution together, you can take it to Kifid. They are registered there and have accepted binding advice, so a Kifid ruling binds them.

Three advisors, or one conversation

With three separate advisors
With TaxSaversOur way
Agreement
With three separate advisorsThe notary writes the agreement and never sees the policy
With TaxSaversWe read the buy-out clause and the valuation clause with it
Policy
With three separate advisorsThe insurer sets up cover without reading the agreement
With TaxSaversOur associated company checks application and policy against that clause
Tax
With three separate advisorsThe accountant sees the tax only after the payout
With TaxSaversYour tax advisor reads the policy before you sign it
Value
With three separate advisorsNobody re-tests the sum insured against what the company is worth
With TaxSaversWe re-test the sum insured against what your company is worth now
Three documents, three people

Reviews

What internationals say

Read our reviews on Google

Quick, very clear and thorough report that answered all my questions about my Dutch tax situation. Highly recommended!

V
Vidar Bruland
Tax advice · October 2025

Professional and on time services !! Thank you Nienke. Certainly I will continue filling my tax return with TaxSavers

G
George Antoniadis
Income tax return · April 2025

Exceptional service! i’ve used other tax agencies and this one is by far the most efficient, speedy and friendly! Can’t recommend them enough

G
Gokul S
Tax services (general) · July 2025

Questions we hear from co-owners

These come up in almost every first call about funding a buy-out. Ask Kim

What is business partner insurance?
Business partner insurance (compagnonsverzekering) is life cover that funds a buy-out between co-owners. If one owner dies, the payout gives the others the money to buy the share from the heirs. The obligation to buy comes from your agreement. The insurance is what pays for it.
Should the policy belong to my BV or to me personally?
That depends on your legal form and on what your agreement asks the survivor to do. Both routes exist and each one changes the tax outcome. We read your documents and put the tax reasoning in writing.
Is the payout free of inheritance tax?
Only if someone other than the person who died owed the premium. The insurer has to have recorded that liability. It also has to show on the signed and dated application form. It has to show on the policy as well. The tax authority can also read two crossing policies as one construction. So it is a condition to meet, not a promise to make.
How much cover do we need?
Start from what the survivor would have to pay for your share, plus any business debt in your name. Your agreement may fix that value, set a formula or leave it to a valuer at the time. We work from your own figures rather than a standard table.
My accountant and my notary already handle this. Why involve you?
We read all three together. The agreement, the policy and the tax each sit with a different advisor. Bring what you already have and we will tell you whether it lines up. If it does, we say so.
What does the advice cost?
The first call is free and takes about twenty minutes. Your advisor discusses what fits your situation in that first conversation. You choose what to do afterwards.
What if my co-owner or my heirs live outside the Netherlands?
A co-owner or heir abroad changes the tax question, not the cover. You can still write the policy crossways. Who taxes the payout depends on residence and on any treaty. We check that with you before you sign.
Are you authorised to give mortgage and insurance advice?
TaxSavers advises on tax, not on mortgages, insurance or pensions. For those we work with A&H Finance, a trade name of New Business Group B.V. They hold the AFM licence (12017511) and they advise and arrange. We introduce you and take on the tax that follows.

Know where your agreement stands

Book a free call. We read what you have, outline the two routes and talk through what fits you.

You decide after that. You’re not committing to anything.

What's included

  • Cover advice and tax advice, matched to each other

  • Your agreement read alongside the policy

  • Help in English or Dutch